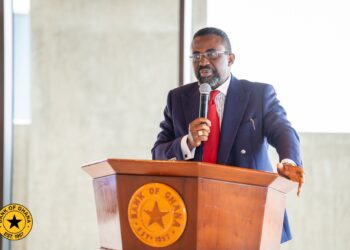


Finance Minister Dr Cassiel Ato Forson has announced the early redemption of GH¢29 billion in Domestic Debt Exchange Programme (DDEP) bonds due in February 2027, assuring bondholders that government has secured the funds to meet its repayment obligations.
The early redemption, effective Thursday, November 12, 2026, forms part of measures to clear upcoming domestic debt obligations and restore confidence among investors who participated in the previous government’s debt restructuring programme.
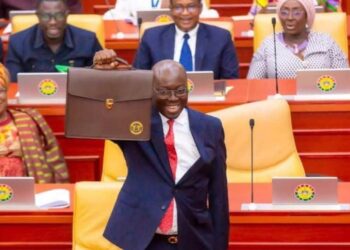
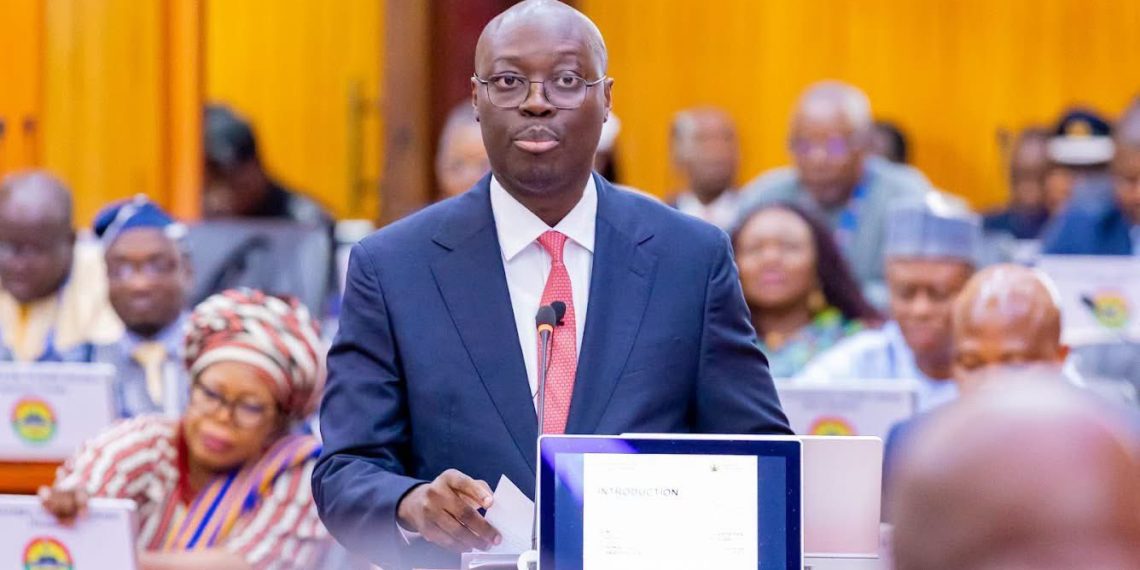
Presenting the 2027 Budget Statement and Economic Policy to Parliament, Dr Forson said the Cedi Sinking Fund had accumulated sufficient resources to cover the principal amount falling due in February.
“The cash is ready,” the Finance Minister declared, urging affected bondholders to come forward for their payments.
He also gave an assurance to other DDEP bondholders that government would honour all outstanding obligations, including principal and interest, in full and on schedule.
“To every other DDEP bondholder, hear me clearly: every cedi owed to you, principal and interest, will be paid in full and on time,” he said.
GH¢53bn repayment obligations in 2027
The early redemption announcement comes as government prepares to meet approximately GH¢53 billion in DDEP bond obligations falling due in February and August 2027.
According to Dr Forson, GH¢40.1 billion in DDEP bonds will mature in February 2027, comprising GH¢29 billion in principal and GH¢11.1 billion in interest.
A further GH¢12.5 billion will fall due in August 2027, consisting of GH¢3.3 billion in principal repayments and GH¢9.2 billion in interest.
The Finance Minister disclosed that as of November 11, 2026, the Cedi Sinking Fund Account held GH¢29 billion, sufficient to cover the entire principal repayment due in February.
He added that government was building adequate financial buffers in the Debt Service Reserve Account to meet the GH¢11.1 billion interest obligation in February and subsequent interest payments.
The arrangement is intended to ensure that government meets its repayment commitments without creating additional pressure on its finances when the bonds mature.
Government reports GH¢41.36bn in DDEP payments
Dr Forson also outlined payments already made to domestic bondholders since 2025, saying government paid GH¢10.8 billion on August 18, 2026, to settle the seventh coupon under the DDEP and the third full cash payment.
The payment brought total disbursements to DDEP bondholders since 2025 to GH¢41.36 billion.
Government has also continued servicing its external debt obligations, with the Finance Minister disclosing that US$700 million was paid to Eurobond holders on July 2, 2026.
That payment increased total Eurobond payments since 2025 to US$2.1 billion.
He further assured Parliament that government had met all obligations to domestic bondholders who declined to participate in the debt exchange programme.
Ghana moves closer to completing debt restructuring
Beyond the domestic repayment commitments, the Finance Minister said government was making progress towards concluding the broader debt restructuring exercise initiated nearly four years ago.
He acknowledged that negotiations had been complicated by the number and diversity of creditors involved but maintained that government remained committed to securing agreements that protect Ghana’s financial interests.
According to him, Ghana has signed bilateral debt restructuring agreements with 16 of the 24 countries with which it is required to execute such arrangements.
Four additional agreements are expected to be signed by the end of December 2026.
Dr Forson said the outstanding debt requiring restructuring represents a relatively small portion of the country’s overall public debt portfolio.
Government intends to intensify negotiations with the remaining creditors and obtain the necessary approvals to complete the process.
He stressed that the outstanding negotiations would be conducted in line with the principles of comparable treatment of creditors and Ghana’s broader debt sustainability objectives.
The early redemption of the GH¢29 billion bonds therefore represents a significant step in government’s efforts to meet upcoming domestic debt obligations while advancing the broader process of restoring confidence in Ghana’s debt management framework.