














…as BoG Governor Pushes Four Reforms to Tackle Payment Risks
Ghana’s mobile money transactions exceeded GH¢519 billion in August 2026, reflecting a 46.5 per cent year-on-year increase and intensifying calls for stronger consumer protection, cheaper cross-border transfers and improved regulation of digital financial services.
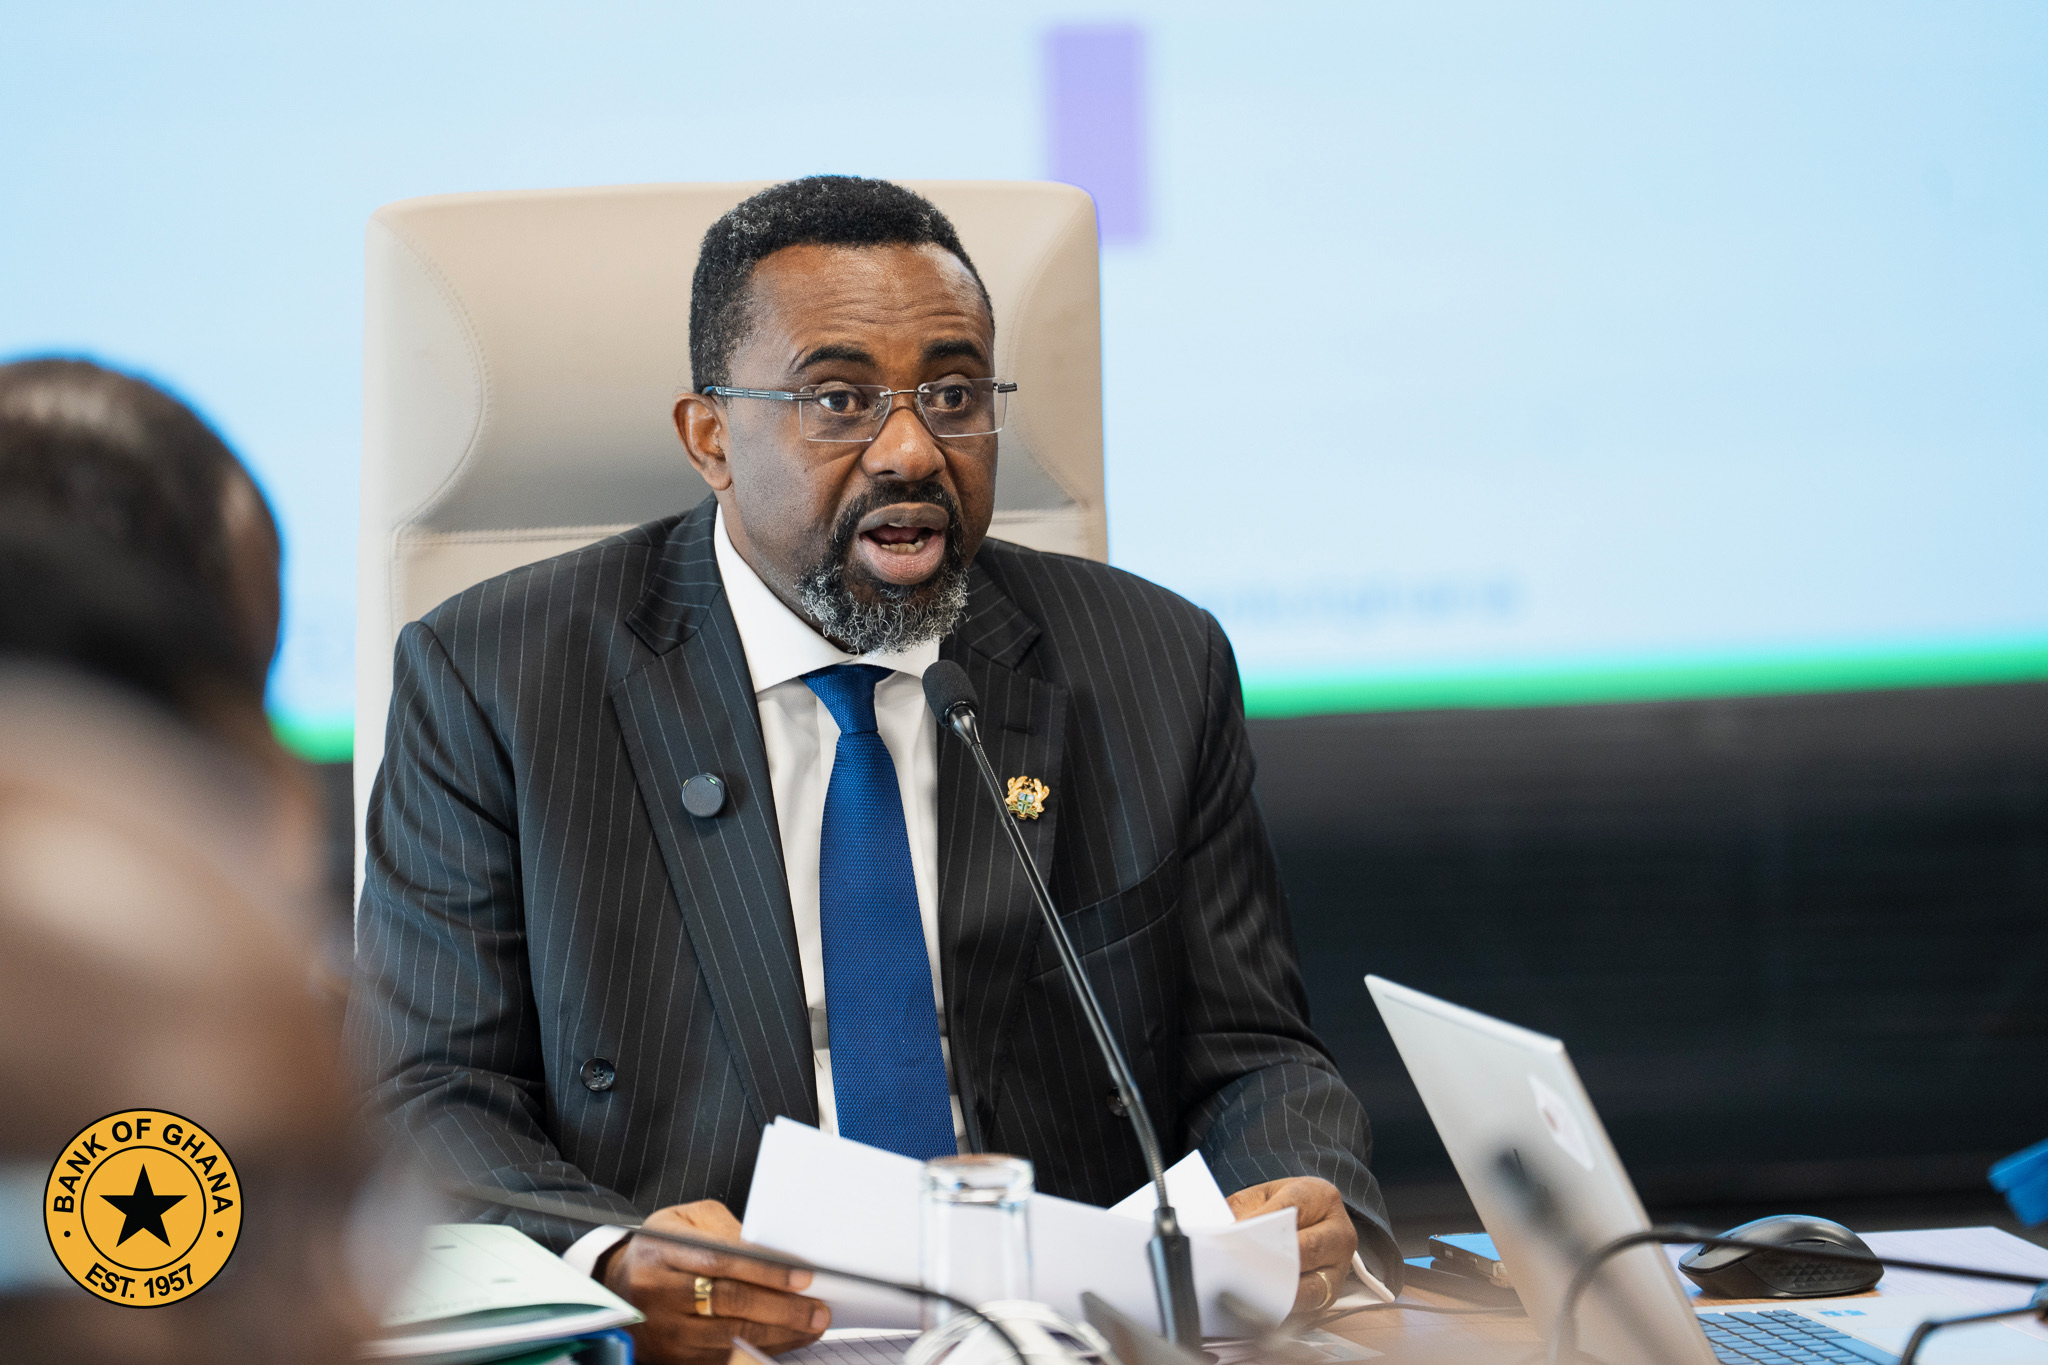
The Governor of the Bank of Ghana (BoG), speaking at the IMF-World Bank meetings in Thailand, said the rapid growth of digital payments across Africa must be matched by reforms that ensure the technology supports trade, investment and meaningful financial inclusion.
He outlined four priorities for strengthening the continent’s digital payments ecosystem: improving cross-border transactions, deepening financial inclusion, protecting consumers and harmonising financial regulations across African markets.
The Governor said the scale of Ghana’s mobile money activity demonstrated the opportunities digital finance offered, but stressed that expanding transaction volumes alone would not guarantee broader economic benefits.
Cross-border transfers remain expensive
The BoG Governor identified the high cost and slow speed of cross-border payments as a major obstacle to trade and financial integration in Africa.
He noted that many transactions between African countries still rely on correspondent banks outside the continent, with transaction costs exceeding 8 per cent, compared with the international target of 3 per cent.
To address the challenge, the Bank of Ghana is testing cross-border payment interoperability along the Ghana–Rwanda and Ghana–Nigeria corridors using central bank digital currencies, stablecoins, bank accounts and mobile wallets.
The central bank has also extended the Pan-African Payment and Settlement System (PAPSS) to mobile wallets on the Ghana–Nigeria corridor.
The Governor said the objective was to transition these initiatives into live services by leveraging existing payment infrastructure rather than creating competing systems.
Financial access yet to translate into full inclusion
Despite the rapid expansion of digital financial services, the Governor said significant gaps remained between access to financial products and their effective use.
He cited figures showing that 81 per cent of Ghanaian adults had access to financial services, but only 52.7 per cent qualified as financially included when actual usage and service quality were considered.
Private sector credit also remains at about 10 per cent of gross domestic product (GDP), highlighting the need for digital platforms to do more than facilitate payments.
According to him, digital financial services should enable people and businesses to save responsibly, access credit, obtain insurance and make investments.
The Bank of Ghana is strengthening oversight of digital lenders and developing tools to monitor borrowers’ exposure to multiple lenders.
Its open banking initiative is also advancing towards a pilot phase, with the aim of giving customers greater control over their financial data and encouraging competition among service providers.
Fraud concerns put consumer protection in focus
The Governor also raised concerns about rising digital financial fraud, disclosing that reported fraud cases in Ghana increased by 48 per cent in 2025.
Although the number of reported incidents rose, the total value at risk remained broadly unchanged, suggesting a shift towards a greater number of smaller incidents affecting ordinary users.
He said addressing the problem would require stronger consumer education, payee confirmation mechanisms, tighter controls on SIM replacement and enhanced cybersecurity supervision.
The measures are intended to strengthen public confidence in digital payment systems as more individuals and businesses depend on mobile money and other financial technologies for everyday transactions.
BoG seeks regulatory cooperation across Africa
The fourth priority focuses on reducing regulatory fragmentation, which the Governor said increases costs for fintech companies seeking to operate across multiple African markets.
He explained that businesses can face duplicative licensing requirements in different countries, even when their activities and risk profiles are similar.
Ghana’s Licence Passporting Framework with the National Bank of Rwanda was cited as an example of how regulatory cooperation could ease market entry while maintaining appropriate safeguards.
The Bank of Ghana is engaging more than ten countries to join the initiative.
The Governor also called for common standards covering payment messaging, payee verification and fraud data sharing to improve interoperability and strengthen regional financial integration.
He stressed that Africa’s digital payments future should not depend on any single technology, but on systems that are safe, efficient, resilient and inclusive.
The proposed reforms are expected to support the continent’s broader trade and investment ambitions while ensuring that the rapid growth of digital finance translates into tangible benefits for consumers and businesses.