The recent revocation of UT Bank’s license by the Bank of Ghana has reignited discussions about corporate governance and regulatory oversight in Ghana’s financial sector. The central bank’s decision, which cited weak capitalization, poor governance, and failure to meet minimum capital requirements, marks a significant chapter in the country’s banking industry.
Founded in 1997, UT Bank was once regarded as a trailblazer in financial inclusion and innovative banking services. However, years of financial struggles and regulatory lapses ultimately led to its downfall. The announcement of its closure has sparked widespread reactions, with financial analysts questioning whether stronger interventions could have prevented the crisis.
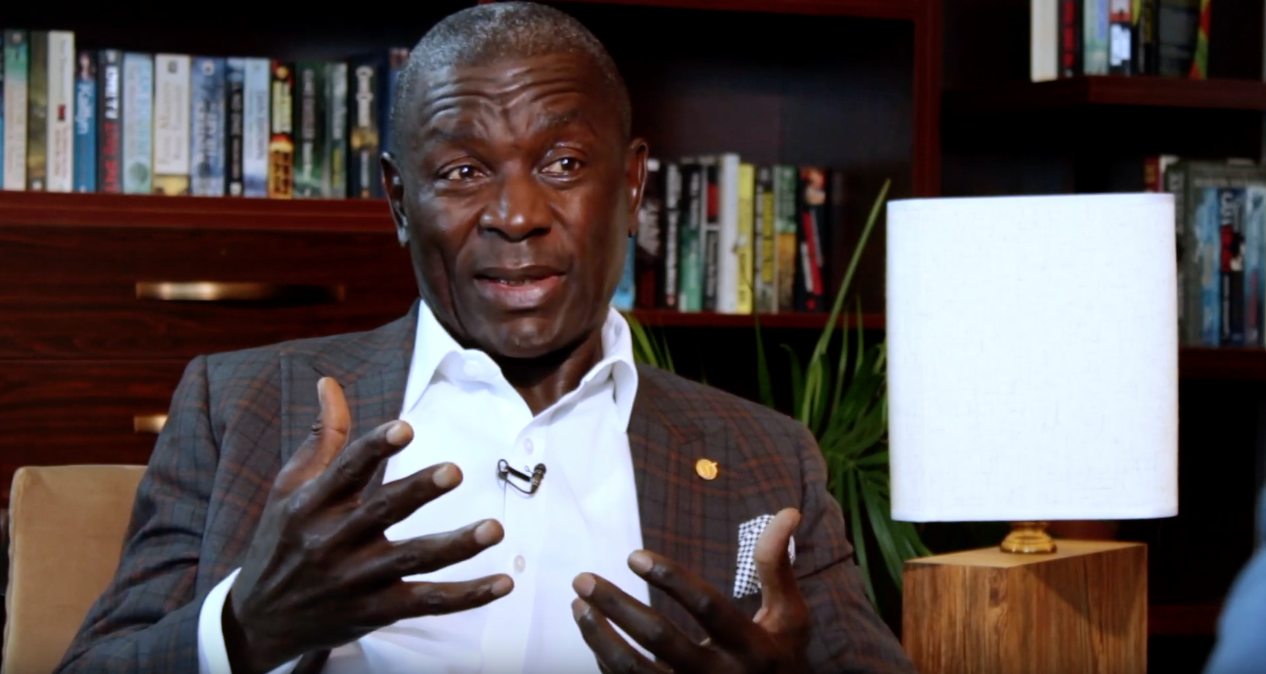
UT Bank’s founder, Kofi Amoabeng, expressed disappointment over the development, acknowledging the bank’s difficulties but emphasizing his willingness to engage with regulators on the way forward. The revocation has also raised concerns about the broader financial ecosystem, with experts calling for enhanced regulatory oversight to prevent similar failures in the future.
In response, the Bank of Ghana has assured the public of its commitment to financial stability, vowing to enforce stricter regulations and accountability measures. As the dust settles on UT Bank’s collapse, the incident serves as a cautionary tale on the importance of strong corporate governance and proactive regulatory intervention in safeguarding Ghana’s banking sector.