Economist and University of Ghana Business School (UGBS) lecturer, Prof. Agyapomaa Gyeke-Dako, has downplayed concerns over the recent depreciation of the cedi, describing the pressures on the local currency as temporary and consistent with seasonal economic trends.
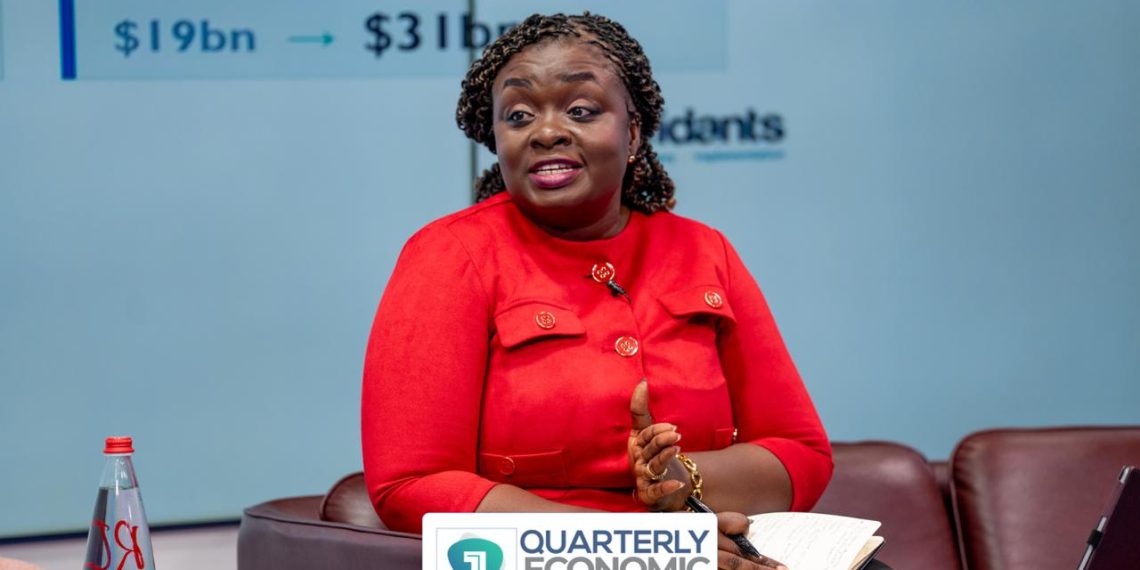
Speaking on Channel One TV’s Quarterly Economic Outlook on Thursday, July 9, Prof. Gyeke-Dako said Ghana’s economy remains on a stable path despite a weaker second quarter compared to the first three months of the year.
She explained that the recent exchange rate movements were largely driven by increased demand for foreign exchange from multinational companies repatriating profits after closing their first-quarter financial accounts.
According to her, such developments are common during the second quarter and should not be interpreted as signs of a deteriorating economy.
Prof. Gyeke-Dako also pointed to geopolitical tensions in the Middle East as another factor that increased demand for foreign currency.
She noted that disruptions around the Strait of Hormuz, through which a significant share of global crude oil passes, contributed to higher oil prices and increased the amount of foreign exchange required by Ghanaian importers.
“You also look at what was happening with the conflict in the Middle East. We are a net importer of oil. About 20 percent of global crude passes through the Strait of Hormuz. Once there are disruptions over there, crude oil becomes limited in supply, driving up prices.
“Our importers therefore need more foreign exchange to import the oil, and that also contributed to the exchange rate pressures,” she said.
Despite these challenges, the economist expressed confidence that Ghana’s improved foreign exchange reserves and the Bank of Ghana’s interventions would help stabilise the currency.
She said the country’s stronger reserve position has boosted investor confidence and strengthened Ghana’s ability to withstand temporary external shocks.
Prof. Gyeke-Dako acknowledged that economic activity between April and June was not as robust as in the January-to-March period but maintained that the overall outlook for the economy remains positive.
“So I think all in all, I am not really worried. January to March was better than April to June but I’m not very concerned,” she stated.
She urged observers to assess recent economic developments within the broader context of ongoing reforms and improving macroeconomic fundamentals rather than focusing solely on short-term fluctuations in the exchange rate.