Ghanaian President John Dramani Mahama has revealed that Ghana is making significant strides in stabilizing its economy, with key debt reduction measures beginning to yield visible results.
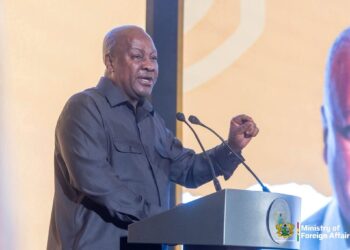
Speaking during a panel session at the 60th Annual General Meeting of the African Development Bank Group in Abidjan, Ivory Coast, Mahama disclosed that the government has slashed the country’s total debt by nearly GH¢150 billion over the past five months.
This, he said, represents a turning point in Ghana’s journey toward economic recovery, especially after years of mounting debt and fiscal pressure. “If this trajectory continues, we could reach our target of 55 to 58 percent debt-to-GDP ratio by the end of this year, ahead of the 2028 goal,” Mahama declared.
He noted that the country’s recent debt exchange programme has been crucial in achieving these gains. The initiative, which involved restructuring debts and extending repayment timelines, was completed earlier this year with bilateral creditors. As a result, Ghana’s debt-to-GDP ratio has dropped to around 75 or 76 percent, with over 97 percent of the total debt now restructured.
“The restructuring has created the fiscal space we need to reinvest in productive sectors of the economy,” Mahama stated, emphasizing that the aim is not just to reduce debt, but to ensure sustainable growth through prudent fiscal management.
He advocated for “smart borrowing,” arguing that future debts should be tied to income-generating investments. “When you borrow, create debt escrows so that the income generated from those projects can automatically service the debt,” he advised.
Mahama’s remarks come as the Ghanaian cedi shows signs of stability, further reinforcing optimism about the economy’s direction. As Ghana navigates the aftermath of financial turbulence, Mahama’s tone suggested cautious optimism, coupled with a strong call for disciplined economic management moving forward.