As Ghana officially launches its ambitious 24-Hour Economy policy today, industry players are raising red flags over a fresh 2.45% electricity tariff hike, warning it could undermine the initiative’s promise of economic transformation.
The tariff adjustment, announced by the Public Utilities Regulatory Commission (PURC), is attributed to exchange rate volatility, rising inflation, surging fuel prices, and higher operational costs. But for many businesses, the timing could not be worse.
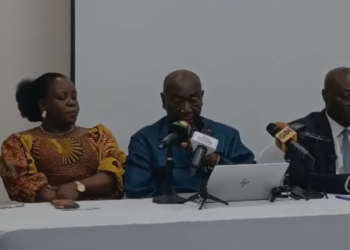
Tsonam Akpeloo, Greater Accra Regional Chairman of the Association of Ghana Industries (AGI), said in an interview with Citi News that the tariff increment poses a direct threat to the operational viability of the extended work model the government is promoting.
“The 24-hour economy implies longer working hours and more energy consumption,” Akpeloo noted. “A 2.5% increase may sound modest, but under a system where factories and facilities operate around the clock, the actual power bill could double.”
He emphasized that the cost implications go beyond electricity bills, warning that increased production costs would ripple through the economy.
The Ghana Union of Traders Association (GUTA) has also raised concern. President Dr. Joseph Obeng said traders were being pushed to the edge, with no option but to pass the increased costs on to consumers.
“We’re reaching a point where every new cost ends up at the final price point,” he said. “Plastic manufacturers, for example, have already increased prices due to tax hikes. We’ll see this pattern repeat across sectors.”
The policy shift to a 24-hour economy, a flagship programme of the Mahama administration, is intended to combat unemployment and spur industrial growth by encouraging continuous operations in key sectors. But AGI and GUTA say this goal will remain elusive if the cost environment continues to harden.
They are urging the government to assess the broader implications of rising utility costs on productivity, job creation, and inflation.
As the 24-hour model rolls out, all eyes will be on how policymakers balance the vision of economic revitalization with the pressing concerns of industry players who fear the financial realities could stifle the very growth the policy seeks to unlock.