Community banks across Ghana have begun implementing sweeping regulatory changes introduced under the Bank of Ghana’s Revised Microfinance Sector Framework 2026, with institutions working to meet new capital requirements and complete mandatory rebranding exercises before the end-of-year deadline.
The reforms, which officially convert all Rural and Community Banks into Community Banks, form part of a broader effort by the central bank to modernise Ghana’s microfinance sector and strengthen financial inclusion nationwide.
While the Association of Community Banks has welcomed the changes, it acknowledges that meeting the new regulatory requirements—particularly the increased minimum capital threshold—will pose challenges for some institutions.
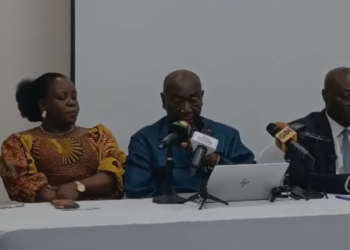
Speaking to Citi Business News, Executive Director of the Association of Community Banks, Solomon Amankwah, said the sector understands the need for reforms designed to make financial institutions stronger and more resilient.
“It is established that Bank of Ghana is our regulator and time and time again they come out with industry regulation that will guide the sector into making us stronger and more resilient,” he said.
Mr. Amankwah explained that the transition is part of a long-term restructuring process aimed at aligning the sector with current economic realities and the evolving needs of customers.
“Being in existence for 50 years, it is time for us to look into ourselves and our activities and try to reshape the sector to resonate with current situations,” he noted.
Under the new framework, all community banks are required to complete statutory name changes, corporate rebranding and other compliance measures by December 2026.
In addition, institutions must meet a new minimum capital requirement of GH¢5 million, representing a fivefold increase from the previous GH¢1 million threshold.
Mr. Amankwah described the capital requirement as one of the most demanding aspects of the reforms, noting that some banks are still mobilising resources to comply.
“When it comes to the capital requirement, it’s a difficult one. To come by 5 million within a split of one year is not easy,” he said.
According to him, while several banks have already achieved the required capital levels, others are actively implementing plans to meet the deadline.
“Some of them have already met the 5 million capital requirement; others are preparing hard to meet the deadline,” he stated.
As part of the compliance process, all community banks are expected to submit capital mobilisation plans to the Bank of Ghana by June 30. The central bank will review progress in September before conducting a final assessment at the end of December.
The Association says it will continue engaging regulators throughout the transition period, even as concerns persist over whether all institutions will be able to satisfy the new capital requirements within the stipulated timeframe.
Industry observers believe the reforms could significantly strengthen the financial health of community banks, improve public confidence in the sector and enhance their ability to support economic development in communities across Ghana.