Ghana’s oil palm industry has the potential to significantly expand its contribution to the economy, but a 150,000-metric-tonne shortfall in crude palm oil supply is limiting the sector’s ability to meet domestic demand, the Oil Palm Development Association of Ghana (OPDAG) has said.
OPDAG President Paul Kwabena Amaning said Ghana currently produces about 250,000 metric tonnes of crude palm oil annually, compared with estimated domestic demand of 400,000 metric tonnes.
He said closing the gap would require increased local production, more efficient processing and improved competitiveness across the oil palm value chain.
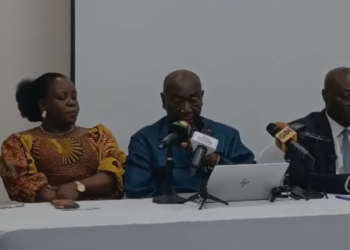
Mr Amaning made the remarks at a one-day stakeholders’ workshop on the oil palm sector, where participants discussed financing and digital financial services as tools for improving the industry.
Financing small operators
Mr Amaning said a proposed $500 million oil palm development financing programme could help address some of the constraints facing the sector.
However, he stressed that financing arrangements must reflect the different needs of businesses across the value chain, particularly smallholder farmers, aggregators and artisanal processors.
He said artisanal processors play an important role in local palm oil production, employment and rural economic activity but often struggle to access affordable financing, modern equipment and formal business support.
“As OPDAG President, I consider the inclusion of these small operators particularly important,” he said.
The industry currently has an estimated 360,000 hectares under cultivation and supports approximately 631,000 people, highlighting its importance to livelihoods and the wider economy.
Digital finance seen as growth tool
Mr Amaning also called for greater use of digital financial services to improve transactions and financial inclusion throughout the oil palm value chain.
He said farmers, aggregators, processors, traders, transporters and exporters all depend on secure and timely payments, making digital finance an important part of efforts to modernise the industry.
According to him, digital financial services could strengthen payment security and record-keeping while improving transparency and creating opportunities for businesses to access savings, credit, insurance and other financial products.
He cautioned, however, that digitalisation should go beyond simply transferring transactions to mobile platforms.
The sector, he said, also requires reliable network connectivity, affordable transaction charges, accessible payment agents, interoperable payment systems, effective consumer protection and practical education for users.
Digital records could support access to credit
Mr Amaning further argued that reliable digital transaction records, subject to appropriate consent and safeguards, could give financial institutions better information about small businesses and their financing needs.
“Such records will help guarantee credit, but they can support more informed financial decisions,” he said.
He called for stronger collaboration among government agencies, financial institutions, fintech companies, mobile network operators, oil palm mills, buyers and industry associations to transform the sector.
He also said ongoing discussions on traceability and revenue assurance systems could provide an opportunity to strengthen industry records and improve access to financial services.
Mr Amaning stressed that policies and financing solutions would be more effective if the views of farmers, processors and other participants in the value chain were incorporated into their design.