











The Bank of Ghana (BoG) has warned commercial banks that high levels of non-performing loans (NPLs) remain a major constraint on lending and has set a December 2026 deadline for financial institutions to bring their NPL ratios below 10 per cent.
The Central Bank said reducing bad loans was critical to restoring confidence in the banking sector, freeing up resources for businesses and ensuring sustainable economic growth.
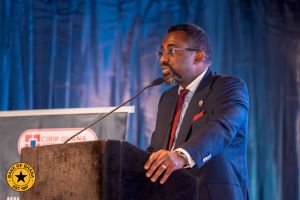
Governor of the BoG, Dr Johnson Pandit Asiama, issued the warning at a high-level forum organised by the Chartered Institute of Restructuring and Insolvency Practitioners (CIRIP), Ghana, in Accra.
The forum, supported by the BoG, focused on the financing of distressed companies and the role of NPL management, International Financial Reporting Standards (IFRS 9) and prudential regulations in corporate recovery.
Dr Asiama disclosed that although the banking sector had recorded progress in reducing bad loans, the current levels remained above acceptable limits.
He said the NPL ratio had fallen to 16.1 per cent by June 2026 from more than 23 per cent in 2025 following several regulatory interventions introduced by the Central Bank.
“That is progress and not sufficiency, and 16.1 per cent remains too high, even if it is fully provisioned,” he said, insisting that all regulated financial institutions must reduce their NPL ratios to no more than 10 per cent by the end of December 2026.
The Governor explained that excessive bad loans weakened banks’ ability to provide credit, increased loan recovery costs and placed pressure on their capital, particularly affecting small businesses and other high-risk borrowers.
He said the drive to reduce NPLs was therefore not only a regulatory obligation but also a key part of efforts to support economic recovery and expand access to finance.
Dr Asiama noted that the Central Bank’s June 2025 directive required regulated financial institutions that failed to meet the 10 per cent threshold after December 2026 to notify the regulator within 10 days and submit a board-approved plan to reduce their NPL levels.
On supporting distressed businesses, the BoG Governor said Ghana’s Insolvency and Restructuring Act provided an opportunity to rescue viable companies rather than resorting to liquidation.
He, however, cautioned banks against using restructuring as a way of hiding losses, stressing that rescue financing must be based on proper assessments of whether a company had realistic prospects of recovery.
“Rescue must begin with a credible test of viability; banks must distinguish between firms facing temporary cash flow shocks and those postponing inevitable failure,” he said.
Dr Asiama advised financial institutions providing post-commencement financing to distressed firms to closely monitor such funds and ensure they were used for productive purposes, including maintaining operations, retaining workers and completing business obligations.
He called for stronger cooperation among banks, insolvency practitioners, accountants and regulators to develop a transparent and risk-sensitive framework for financing companies under distress.
Meanwhile, the Chairman of the occasion and Board Chair of Scancom PLC (MTN Ghana), Dr Ishmael Yamson, acknowledged the improvement in NPL levels but warned that some regulatory measures could discourage banks from supporting distressed businesses.
He argued that financing provided under approved rescue plans should receive special consideration under NPL calculations and restrictions on loan growth to encourage banks to participate in corporate recovery efforts.
According to him, banks should not be penalised for supporting businesses through structured rescue arrangements aimed at preserving jobs and economic value.
Dr Yamson stressed that while rescue financing was necessary in some situations, the long-term focus should be on strengthening businesses’ ability to manage risks and avoid financial distress.
He called for a balanced regulatory approach that protects financial stability while allowing viable companies to access funding needed for recovery and growth.