An economist at Aston University in the United Kingdom, Sajid Chaudhry, has warned that reductions in the Bank of Ghana policy rate will have little effect on Ghana’s economic growth unless commercial banks significantly lower their lending rates.
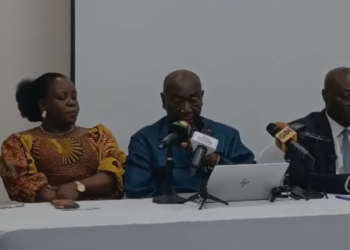
Speaking at a forum on interest rates and economic development in Ghana, Dr Chaudhry said the country’s monetary easing efforts can only stimulate growth if lower policy rates are effectively transmitted into cheaper credit for businesses and households.
“Monetary easing can support growth in Ghana, but only if it is transmitted through lower lending costs, stronger private-sector credit, stable exchange rates, and healthier bank balance sheets,” he stated.
According to him, commercial banks have been slow to reduce lending rates despite recent cuts in the policy rate, limiting the expected benefits of lower inflation and easing monetary conditions.
He explained that analysis of economic data from 2002 to 2024 showed a clear relationship between lower lending rates and stronger Gross Domestic Product (GDP) growth, while high interest rates and inflation tended to weaken economic performance.
Dr Chaudhry attributed the slow reduction in lending rates to persistent non-performing loans, exchange-rate volatility, and broader macroeconomic uncertainty, which continue to force banks to maintain wide interest margins.
“Policy should therefore combine monetary easing with measures that strengthen credit intermediation and bank balance sheets,” he said, while commending the central bank for reducing rates in line with easing inflationary pressures.
The economist further called on the Bank of Ghana to consider regulatory interventions that would encourage commercial banks to pass policy rate reductions more quickly to borrowers.
“The central bank can use some kind of regulatory measures to really persuade banks to translate those monetary policy rate cuts into lending rates,” he suggested.
Responding to questions from journalists, Dr Chaudhry also urged banks to improve loan screening and monitoring systems to reduce bad loans, while encouraging businesses to increase productivity and honour loan repayment obligations.
“When banks have high levels of bad loans, they’re less willing and able to pass lower policy rates through to cheaper lending, which blocks the impact of monetary easing on growth,” he explained.
He additionally called on government to sustain macroeconomic stability through prudent spending, stable exchange rates, controlled inflation, and a resilient banking sector to create conditions for lower lending rates and stronger economic expansion.